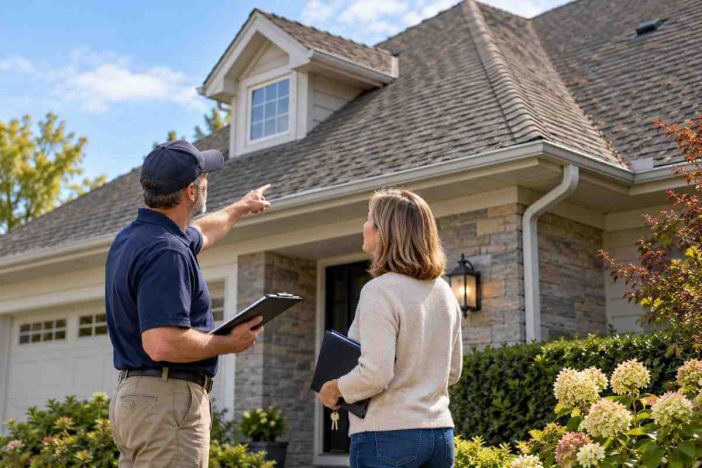
The first estimate says replacement.
The second roofer says the shingles are old but still serviceable.
The third recommends repairing flashing and watching one section over the garage.
Meanwhile, the listing date is three weeks away.
Nothing is dripping from the ceiling.
There is no bucket in the attic.
But the roof is old enough that everyone suddenly has an opinion about it.
That is the moment when a seller can spend a large amount of money solving the wrong problem.
A roof can matter to at least five different people in a transaction: the seller, buyer, inspector or surveyor, lender or appraiser, and insurer.
They do not necessarily evaluate it for the same reason.
That is why the useful question is not simply:
“How old is the roof?”
It is:
“What could this roof prevent the transaction from doing?”
Answer that before deciding whether to replace roof before selling.
Quick Answer: Should You Replace the Roof Before Selling?
Not automatically.
An older roof that is dry, functional, professionally assessed, and supported by credible records presents a different risk from one with active leakage, widespread deterioration, damaged decking, or unresolved moisture evidence.
Before authorizing replacement, establish five things:
- whether the roof is actually failing;
- what an inspector or surveyor is likely to report;
- whether the condition could affect appraisal, financing, or insurance;
- whether targeted repair can resolve the material defect; and
- what evidence you can give the next person evaluating the property.
That approach follows the broader principle in our repair-or-replace framework for home sellers: establish the condition before allowing age or anxiety to determine the scope of work.
Check 1: Is the Roof Failing, or Is It Simply Old?
Age matters.
It helps explain where a roof may sit in its ownership history.
It does not diagnose failure.
A roof installed many years ago may still be performing.
A newer roof can already have problems because of installation defects, storm damage, poor flashing, inadequate drainage, ventilation problems, or material failure.
Before discussing replacement, separate calendar age from current evidence.
Evidence that deserves investigation
Examples include:
- active water entry;
- recurring leak history;
- missing or damaged roofing materials;
- damaged flashing;
- visible sagging or deformation;
- deterioration around penetrations;
- damaged decking identified by a qualified professional;
- moisture evidence in the attic or ceilings;
- repeated patching of the same area;
- a professional finding that a larger system failure exists.
The presence of one item does not automatically mean the entire roof needs replacement.
It means the seller finally has a real question to investigate.
Age without a known defect
An old roof with no obvious leak still deserves attention before listing.
But attention can begin with inspection and documentation, not necessarily demolition.
This distinction matters because many online guides convert roof age into a hard replacement threshold.
Real roofs do not age on a universal calendar.
Material, installation quality, climate, ventilation, exposure, maintenance, slope, storm history, and previous repairs all influence condition.
Do not turn a generalized lifespan estimate into a diagnosis of your roof.
Check 2: Find the Defect Before the Buyer Prices the Unknown
A seller can live comfortably with uncertainty.
A buyer under contract usually cannot.
Imagine an inspection report containing this sentence:
Roof covering appears aged. Further evaluation by a qualified roofing professional is recommended.
That wording does not necessarily say:
Replace the roof.
But it creates an unanswered financial question.
Once the scope is unknown, the buyer may mentally price:
- a minor flashing repair;
- hidden water damage;
- roof replacement;
- damaged decking;
- attic remediation;
- closing delays.
All at once.
The cost of uncertainty can therefore become larger than the cost of the actual defect.
This is one reason roof findings frequently become home inspection issues that trigger price negotiations.
Get the scope before negotiating the solution
If a roof concern already exists, a useful pre-listing evaluation should help answer:
- What condition was actually observed?
- Where is the problem?
- Is water entry active or historical?
- Is the issue localized or widespread?
- Is targeted repair technically reasonable?
- Is further structural or moisture evaluation necessary?
- What documentation can be produced after repair?
The objective is not to obtain a flattering “roof certificate.”
It is to reduce the number of things everyone has to guess.
Check 3: Could the Roof Become a Closing Bottleneck?
This is where a roof stops being only a maintenance issue.
The condition can interact with several independent transaction systems.
Buyer
The buyer may accept the roof as-is, ask for repair, request a credit, renegotiate the price, or walk away where the contract permits.
Inspector or surveyor
Their job is to report observable condition and risk—not to protect the seller’s preferred price.
A recommendation for specialist evaluation can create another decision point before closing.
Appraiser or lender
In U.S. conventional lending, Fannie Mae’s current property-condition guidance distinguishes ordinary wear and deferred maintenance from physical deficiencies serious enough to affect safety, soundness, or structural integrity.
The guidance specifically identifies conditions such as active roof leaks and worn roof shingles among examples that may require a different appraisal or completion path when the deficiency rises to the applicable threshold.
That is very different from saying:
“Every roof over a certain age must be replaced.”
It does not.
Our guide to how appraisers evaluate home condition explains the broader distinction between chronological age, condition, maintenance, and effective age.
Insurer
Insurance underwriting is another independent decision.
A seller’s existing policy does not guarantee that a buyer will receive identical coverage on identical terms.
Roof underwriting can vary by:
- carrier;
- state or region;
- roof material;
- condition;
- claims history;
- catastrophe exposure;
- inspection results;
- policy form.
Avoid universal internet rules such as:
“Insurance companies will not insure any asphalt roof over X years.”
That may be true for a particular carrier, market, or policy.
It is not a safe nationwide rule.
If insurability is a concern in your transaction, the buyer should confirm actual requirements with the insurer rather than relying on a generalized age threshold.
The Roof Bottleneck Test
Before spending money, ask which door the roof could actually close.
| Transaction gate | Question to answer | Evidence that helps |
|---|---|---|
| Physical condition | Is the roof actually failing? | Professional roof evaluation |
| Inspection/survey | What visible defect is likely to be reported? | Repair records, photos, inspection |
| Appraisal/lending | Has a property-condition issue been identified? | Appraisal/lender requirements |
| Insurance | Can the buyer obtain acceptable coverage? | Actual insurer underwriting response |
| Negotiation | Is the remaining issue financial rather than physical? | Defined repair scope and quotes |
This is the core editorial distinction.
Do not replace a roof to solve an insurance problem that does not exist.
Do not offer a buyer credit for an active defect that another party requires to be corrected.
And do not spend the price of a full replacement when a qualified evaluation shows that a targeted repair addresses the actual defect.
Check 4: Compare Repair, Replace, Document, or Negotiate
Once condition is known, the seller has more than two options.
Option 1: Repair
Targeted repair makes sense when a defined defect can be corrected without replacing the entire roof.
Examples may include certain localized flashing, penetration, minor material, or drainage-related problems, depending on professional assessment.
A repair is especially useful when it converts:
“There may be a roof problem.”
into:
“This specific defect was identified and corrected.”
Option 2: Replace
Replacement becomes more defensible when evidence shows the roof has broader failure rather than a single repairable issue.
That could include widespread deterioration, recurring water entry, extensive material failure, significant substrate problems, or another condition a qualified professional concludes cannot reasonably be solved through localized repair.
Replacement can also become transaction-driven when a real—not hypothetical—appraisal, lender, insurer, or contractual requirement makes continued use of the existing roof impractical.
Option 3: Document and continue
Some roofs are simply older.
If the roof remains functional and professional evaluation does not identify a material failure, documentation may be the most rational next move.
Useful evidence might include:
- installation date;
- permit information where applicable;
- material information;
- previous repair invoices;
- recent inspection;
- warranty documents;
- storm-repair records;
- dated photos;
- professional notes describing work performed.
Documentation cannot make a bad roof good.
It can make a serviceable roof understandable.
Option 4: Negotiate
A defined roof issue may sometimes be handled through:
- buyer credit;
- price adjustment;
- seller-performed repair;
- negotiated replacement;
- escrow or other transaction structure where permitted.
Whether those options work depends on the contract, lender, jurisdiction, insurer, and actual condition.
A credit is therefore not a universal escape hatch.
The stronger negotiation begins with a known scope, not a guessed replacement cost.
Check 5: Build a Roof Evidence File Before Listing
Roof paperwork is often scattered.
One invoice is in email.
The permit is in a municipal database.
Storm repair photographs are on an old phone.
The material warranty was placed in a drawer five years ago.
Then the inspection happens.
A buyer asks one simple question:
“What has actually been done to this roof?”
The seller should not have to reconstruct the answer during contingency negotiations.
A practical roof evidence file
Collect what legitimately exists:
- installation invoice;
- known installation date;
- permit or final approval where relevant;
- warranty details;
- maintenance or inspection reports;
- repair invoices;
- storm-damage documentation;
- before-and-after photos for significant repairs;
- contractor information;
- records of prior water intrusion and remediation.
If a previous roof leak caused interior damage, organize that history carefully rather than hiding it. Our water damage documentation checklist before selling explains how to separate the original event, source correction, resulting damage, and remediation evidence.
Do not invent missing history
If the installation date is unknown, say it is unknown.
If no permit can be located, do not imply one existed.
If a roofer repaired one valley, do not describe the entire roof as professionally certified.
The strongest file is not the one with the most impressive claims.
It is the one in which every important statement can be explained.
Original Framework: The Roof Transaction Risk Matrix
Use this before authorizing a five-figure project.
| Current situation | Physical risk | Transaction uncertainty | Better first move |
|---|---|---|---|
| Older roof, dry, records available | Low–moderate | Low | Organize records; consider professional assessment |
| Older roof, no records, condition unknown | Unknown | High | Professional evaluation |
| Localized diagnosed defect | Defined | Moderate | Compare targeted repair with broader condition |
| Past leak, source repaired, evidence available | Moderate | Moderate | Document source correction and interior remediation |
| Active leak | High | High | Diagnose and address promptly |
| Repeated leaks in several areas | High | High | Evaluate whether system-wide work is warranted |
| Buyer wants a new roof but no material defect is established | Variable | Negotiation-driven | Review evidence, contract, market strategy |
| Appraiser/lender/insurer identifies an actual requirement | Transaction-specific | High | Resolve the specific requirement before assuming another solution |
The most expensive quadrant is often:
condition unknown + transaction deadline approaching.
That is where sellers lose control.
One Roof, Five Different Audiences
A roof can pass one person’s test and still create questions for someone else.
The roofer asks
What is physically wrong and what work is technically appropriate?
The inspector or surveyor asks
What visible condition, deterioration, moisture evidence, or risk should be reported?
The appraiser asks
How does observable property condition affect the appraisal assignment, marketability, and applicable property requirements?
The insurer asks
Does the property meet this carrier’s underwriting requirements?
The buyer asks
How much uncertainty and future expense am I accepting?
Those are five different questions.
One inspection document may help several audiences.
It does not make all five decisions for them.
Three Seller Scenarios
Seller A: Old Roof, No Active Problem
The roof is older.
There are no known current leaks.
A recent qualified evaluation finds no major active failure.
Installation information and a prior repair invoice are available.
The seller’s question is primarily about future buyer perception.
A defensible strategy may be:
inspect → document → disclose accurately where required → prepare for negotiation.
Full replacement is not automatically the starting point.
Seller B: One Known Repairable Problem
Water enters around a roof penetration during wind-driven rain.
A professional identifies a localized flashing defect and confirms the surrounding roof condition separately.
The seller now has a defined problem instead of a vague “old roof.”
The next step can be based on repair scope rather than fear.
Seller C: Recurring Failure
Leaks have occurred in several areas.
Repairs have been repeated.
Interior staining returns.
Professional evaluation finds broader deterioration.
This is a different risk profile.
The conversation has moved beyond age and buyer psychology.
Replacement may now be more defensible because the evidence describes a system-wide problem.
A Buyer Credit Solves Money, Not Roof Condition
Credits are attractive because they preserve seller cash and give buyers control over future work.
But they solve only one category of problem:
who pays.
A credit does not automatically solve:
- an active leak;
- damaged material;
- an appraisal condition;
- lender eligibility;
- insurance underwriting;
- a buyer’s right under the contract;
- disclosure requirements.
That distinction matters.
If the barrier is purely negotiation economics, a credit can be useful.
If another party requires a physical condition to be resolved, money promised at closing may not solve the barrier.
Confirm the transaction requirement before choosing the financial solution.
Do Not Confuse Roof Cost With Added Home Value
A new roof can improve marketability.
It can reduce uncertainty.
It can eliminate an obvious maintenance concern.
It can remove one future expense from the buyer’s mental budget.
None of those facts means:
replacement cost = increase in appraised value.
An appraiser analyzes the property and market evidence as a whole.
The roof is part of that condition picture.
It is not a receipt that automatically gets added to the home’s value.
This distinction is especially important when a seller is considering a premium roof system immediately before moving.
The incoming buyer may value the new roof.
That does not obligate the market to reimburse every dollar of the seller’s material choice.
U.S. Sellers: Separate Conventional, FHA, Insurance, and Contract Issues
The U.S. transaction can involve several independent rule sets.
For conventional mortgages sold to Fannie Mae, current property-condition guidance permits some properties with ordinary deferred maintenance to be appraised as-is while treating deficiencies affecting safety, soundness, or structural integrity differently.
That framework is condition-based—not simply roof-age-based.
FHA-financed transactions operate under HUD’s Single Family Housing Policy Handbook 4000.1, which has its own property-acceptability and appraisal requirements.
Insurance underwriting is separate again.
And the purchase contract adds another layer.
Do not combine all four into:
“My roof is old, so the bank will make me replace it.”
Instead ask:
- Has a professional identified a roof defect?
- Has the appraiser identified a property condition?
- Has the lender stated a requirement?
- Has the insurer stated an underwriting problem?
- Has the buyer requested work under the contract?
Only then do you know what problem must actually be solved.
If an appraisal is approaching, the broader home appraisal checklist for sellers can help organize roof permits, repair records, improvements, and other major-system evidence without attempting to influence the appraiser’s independent opinion.
UK Sellers: Think Survey Evidence, Not U.S. Appraisal Rules
The vocabulary and transaction process change in England and Wales.
A buyer may obtain an RICS Home Survey, with the level of inspection depending on the property and service selected.
RICS Level 2 and Level 3 services can involve more extensive inspection of the roof space and provide progressively deeper information about visible defects, repairs, maintenance, and condition.
That means a tired roof can become a negotiation issue even though the U.S. language of FHA appraisal conditions is irrelevant.
GOV.UK’s seller guidance also makes an important distinction: sellers should not hide defects. If a significant issue concerns you, the government guide suggests having it professionally assessed; a seller can then consider remedial work or account for the issue in the property’s pricing.
For UK readers, therefore, the decision path is better framed as:
condition → professional assessment → survey risk → conveyancing/disclosure advice → repair or pricing decision.
Not:
American roof age rule → automatic replacement.
Local law, conveyancing practice, lender requirements, and insurance terms should be confirmed in the jurisdiction where the property is being sold.
What Not to Do Before Listing
Do not replace solely because of a generalized age threshold
Age helps frame the investigation.
It should not replace the investigation.
Do not cover interior evidence without solving the source
Painting over a ceiling stain does not answer whether the moisture source is active.
It can also create a much harder buyer-confidence problem if the issue reappears.
Do not ask a contractor to guarantee an unknowable future
A contractor can report observations and work performed.
That is different from promising exactly how many years a roof will remain problem-free.
Do not rely on the seller’s current insurance policy
The buyer’s underwriting decision may be different.
If insurance is a concern, obtain actual transaction-specific information.
Do not let the buyer’s estimate become the first defined scope
If you already suspect a problem, investigate while you still control the timing.
Once the sale is under contingency, every unanswered question becomes part of negotiation.
Trust and Verification
Roof decisions before a home sale can involve physical safety, water intrusion, structural damage, mortgage requirements, insurance, disclosure obligations, and large financial commitments.
For significant concerns:
- use an appropriately qualified roofing professional;
- involve a structural professional when structural condition is in question;
- verify permits with the relevant local authority;
- ask the actual lender about loan-specific property requirements;
- ask the actual insurer about underwriting;
- discuss local disclosure and contractual obligations with the appropriate real-estate or legal professional.
For U.S. sellers, useful primary references include the Fannie Mae Selling Guide. FHA-financed transactions are governed by HUD’s Single Family Housing Policy Handbook 4000.1, which contains FHA’s current Single Family Housing policy requirements.
For sellers in England and Wales, see the government’s How to Sell a Home guidance and the RICS Home Survey consumer guide.
These sources explain transaction frameworks.
None can diagnose the roof on an individual property.
Frequently Asked Questions
Should I replace a 20-year-old roof before selling?
Not solely because it is 20 years old. Material, climate, installation, maintenance, storm exposure, visible deterioration, and current condition all matter. Have the roof evaluated if its condition is uncertain, then decide whether repair, documentation, replacement, or transaction strategy addresses the actual problem.
Can I sell a house with an old roof that does not leak?
Often yes, but a dry roof can still raise inspection, survey, insurance, or buyer questions. Establish its actual condition, collect available records, and confirm transaction-specific financing or insurance issues rather than assuming either that age is irrelevant or that replacement is mandatory.
Is a buyer credit better than replacing the roof?
It can be when the physical condition and cost scope are understood and no lender, appraisal, insurance, contractual, or safety requirement demands another solution. A credit handles money; it does not repair the roof or override requirements imposed by other participants in the transaction.
Will a new roof increase the appraisal by its replacement cost?
Not automatically. A new roof may improve condition and marketability, but appraised value is based on the property and relevant market evidence as a whole. Replacement spending should therefore be evaluated as a risk-removal and marketability decision, not as a guaranteed dollar-for-dollar return.
Make the Roof Understandable Before You Make It New
A roof does not have to be new to be explainable.
That is the seller’s real advantage.
Know whether it leaks.
Know what has been repaired.
Know what a qualified professional observed.
Know which documents exist.
Know whether an actual lender, appraiser, insurer, surveyor, or buyer has raised a condition.
Then decide what the roof requires.
Sometimes that will be replacement.
Sometimes it will be targeted repair.
Sometimes the most rational next step is inspection and documentation.
And sometimes the remaining problem is simply a negotiation over future ownership cost.
When deciding whether to replace roof before selling, spend money where the evidence points—not where uncertainty shouts the loudest.